The middle-class affordability paradox: Wealthy on paper, squeezed in real life
Published in News & Features
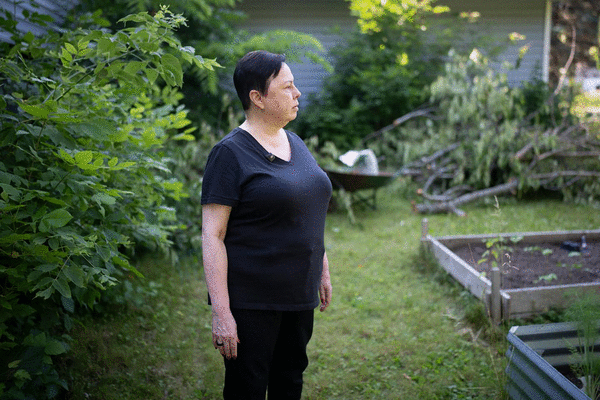
MINNEAPOLIS — Americans have never been richer.
Personal wealth has more than doubled in the past decade, reaching nearly $186 trillion in the second quarter, Federal Reserve data shows.
The most affluent Americans hold a disproportionate share of that wealth, though. For the majority in the middle, much of what they have is tied up in homes and retirement accounts — money that can’t easily pay for a roof repair, medical bills or kids’ sports fees.
That’s the crucial difference between wealth and cash flow. For many middle-income Americans, wealth offers a level of future financial security, while cash flow dictates whether everyday life is affordable.
And with the rising cost of essentials squeezing household budgets, that distinction helps explain why affordability has become a pressing issue for voters in the upcoming midterm elections.
Angela Skrade knows the difference well. Over the past few decades, her finances have toggled from secure to insecure, and back again.
After working multiple part-time jobs during her 22-year marriage, a divorce left her “just kind of scraping by.”
“I had a dramatic shift from being middle-class to not even close to middle-class,” the 55-year-old said.
Skrade now has found her footing thanks to a full-time education role with a pension, bumping her back up into the middle-class. She owns a home and aims to retire at 67, but she’s still working multiple side gigs to get by.
“I do have money I can fall back on, a little bit here and there,” Skrade said, “but most of it’s retirement that I can’t touch.”
For all but the wealthiest Americans, real estate makes up the biggest share of household wealth, followed by investments such as stocks and pensions.
The post-pandemic stock market boom has been good news for investors across income levels, though the wealthiest Americans have reaped the greatest benefits.
The highest-earning 1% of American households hold more of the nation’s wealth than households in the middle 40% combined, with more than half their assets in corporate equities and mutual funds.
As higher-income Americans have gained wealth with the booming stock market, they’ve kept on spending, propping up overall consumer spending numbers despite economic headwinds. Meanwhile, price increases — and the interest rate hikes meant to tame them — are hitting lower-income Americans the hardest.
In the Federal Reserve’s October report of economic conditions across its 12 districts, the central bank wrote “over half of the districts noted that consumer spending was driven by high-income households.”
There’s evidence that some lower-income individuals are taking out more loans, including from their 401(k) plans, to cover their spending needs, that same report in August noted.
Inflation remains below the 2022 peak of more than 9% but consumers are dealing with the cumulative effect of years of high prices, said Anthony Saglimbene, vice president and chief market strategist at Ameriprise Financial.
While the market has “returned incredible performance over the last couple of years,” Saglimbene said, a significant number of Americans aren’t benefiting from that growth. That’s because they either aren’t invested or don’t have a meaningful amount of money in the stock market.
As a result, he said, “they’ve had to face rising prices at the same time that their wealth has not kept up with inflation.”
U.S. Bank’s 2026 Wealth Survey found more than 60% of Generation Z, millennial and Gen X respondents are struggling to make financial progress, and more than half feel they “did everything ‘right’” but are not where they hoped to be financially.
“It’s a weird situation to be in,” said Minneapolis resident Emily, 36, who asked that her last name not be used in order to discuss her finances. “We’re going to retire with a decent amount of money. And also, why are we stressed about hitting our credit card max at Costco this week?”
The opportunity to build wealth through homeownership or modest investments has traditionally been a marker of middle-class life, and a means of helping the next generation move up.
But as middle-income Americans increasingly struggle with daily expenses, many are finding it difficult to save for a down payment or retirement.
A June survey from the Employee Benefit Research Institute showed 59% of working Americans are actively saving, down from 64% in 2025. Most worry they aren’t saving enough, with debt, healthcare expenses and housing costs making it harder to put money aside.
More than 300 people responded to a Minnesota Star Tribune questionnaire this summer about what they believe should comprise a middle-class life, and whether their household can afford those things. Respondents cited homeownership and maintenance, along with saving for retirement, children’s college or an unexpected expense as feeling difficult or impossible to reach.
Many respondents nearing retirement said they’re proceeding cautiously into this next phase of life — when their wealth, built up over a career, turns into income.
With two pensions and two 401(k) accounts, plus Social Security and Medicare, Yolanda Brantley counts herself lucky. And yet, retiring in June at 67 felt “very scary.”
Brantley, of Maple Grove, Minnesota, hoped to retire debt-free but is working to pay off personal and car loans, and said she expects her mortgage will outlive her.
As Brantley makes the transition to a fixed income, she said uncertainty in the economy worries her. And ultimately, there’s only so much she can control.
Retirement is “kind of how I planned it, about 50%,” she said. “The other 50% is really an unknown. I’ve never been retired before.”
©2026 The Minnesota Star Tribune. Visit startribune.com. Distributed by Tribune Content Agency, LLC

Comments