Not in a FEMA flood zone? Your home could still be at risk – and you could suffer more than your neighbor
Published in News & Features
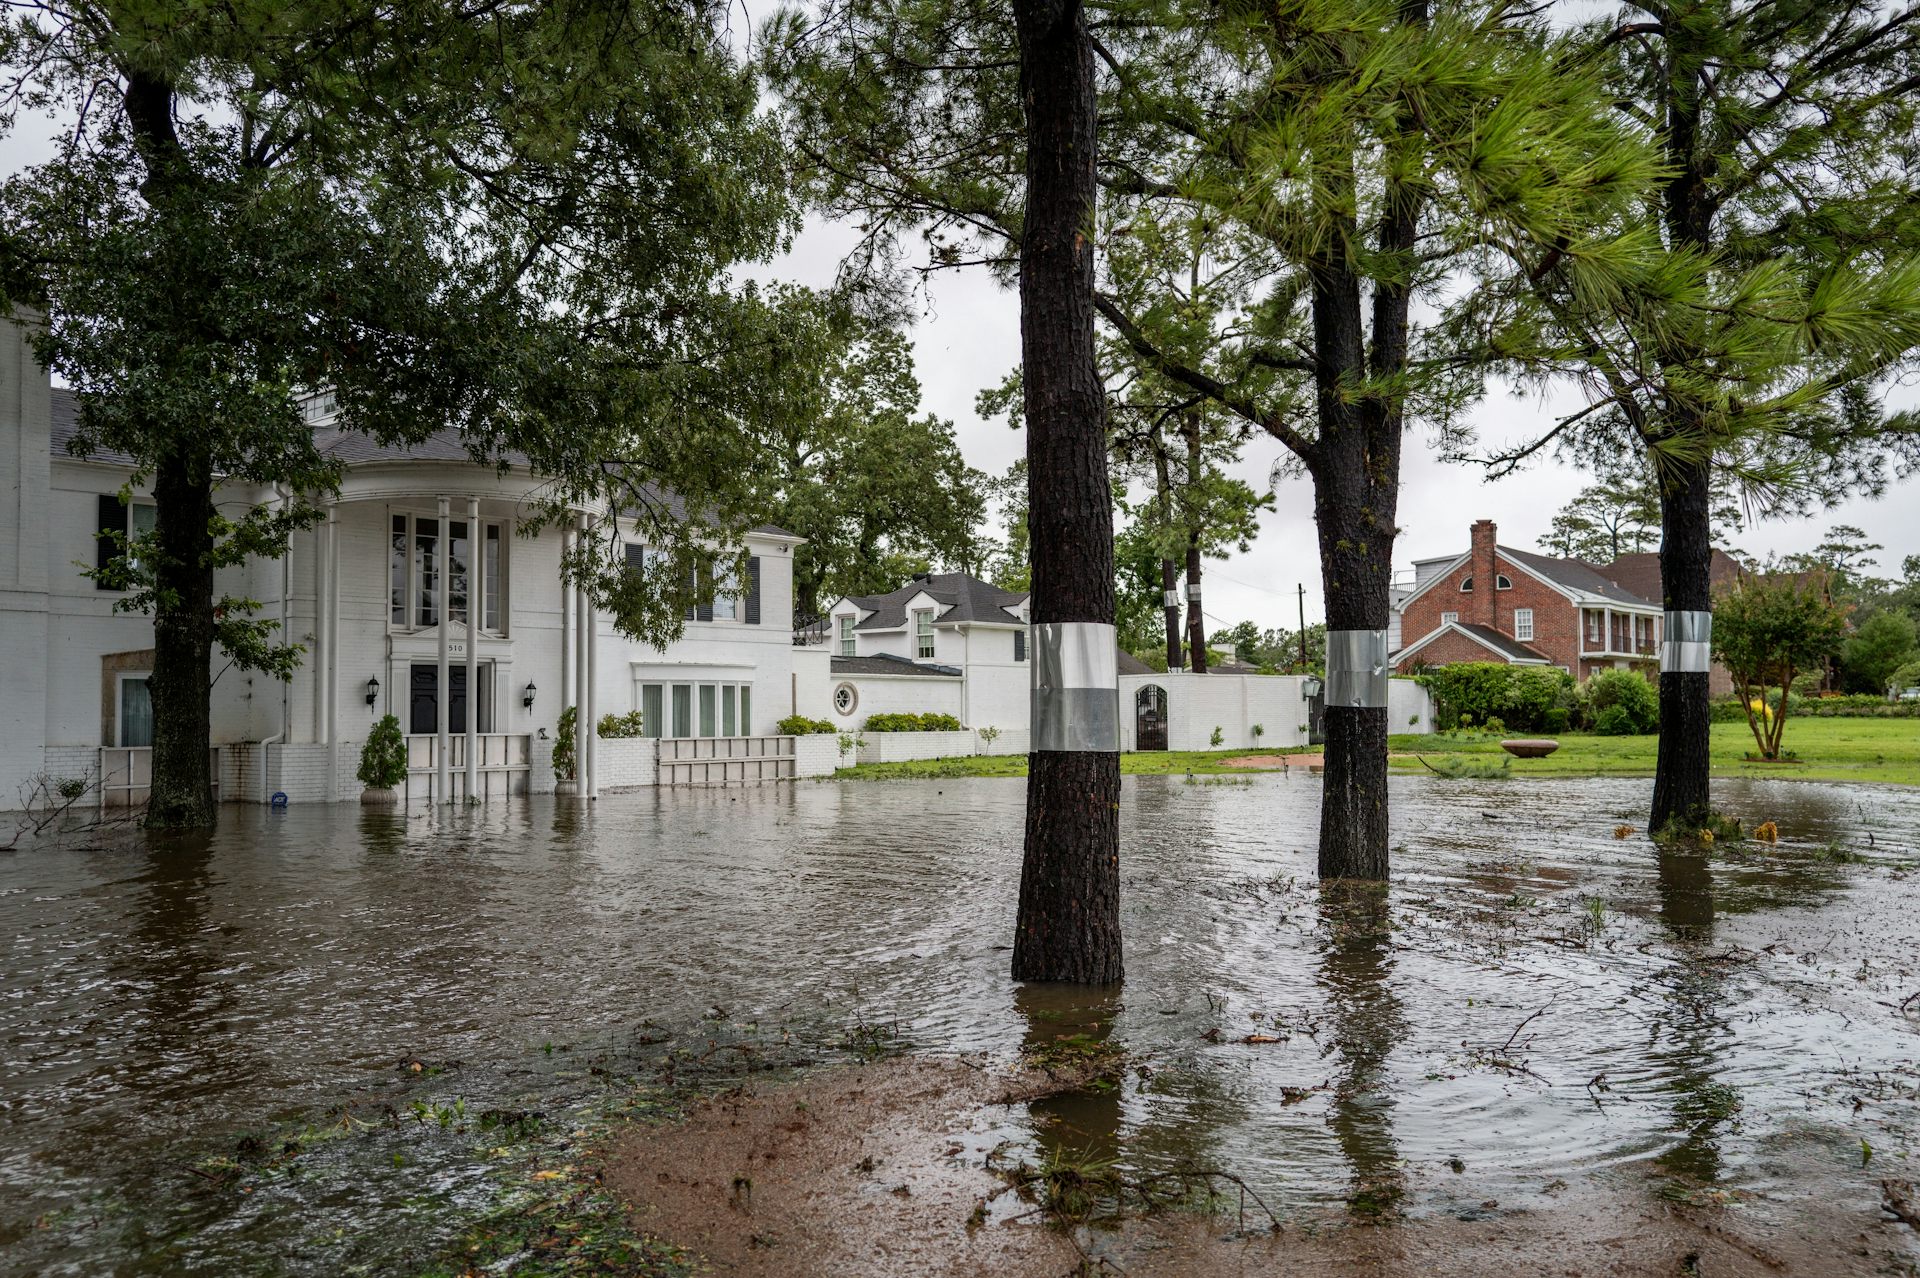
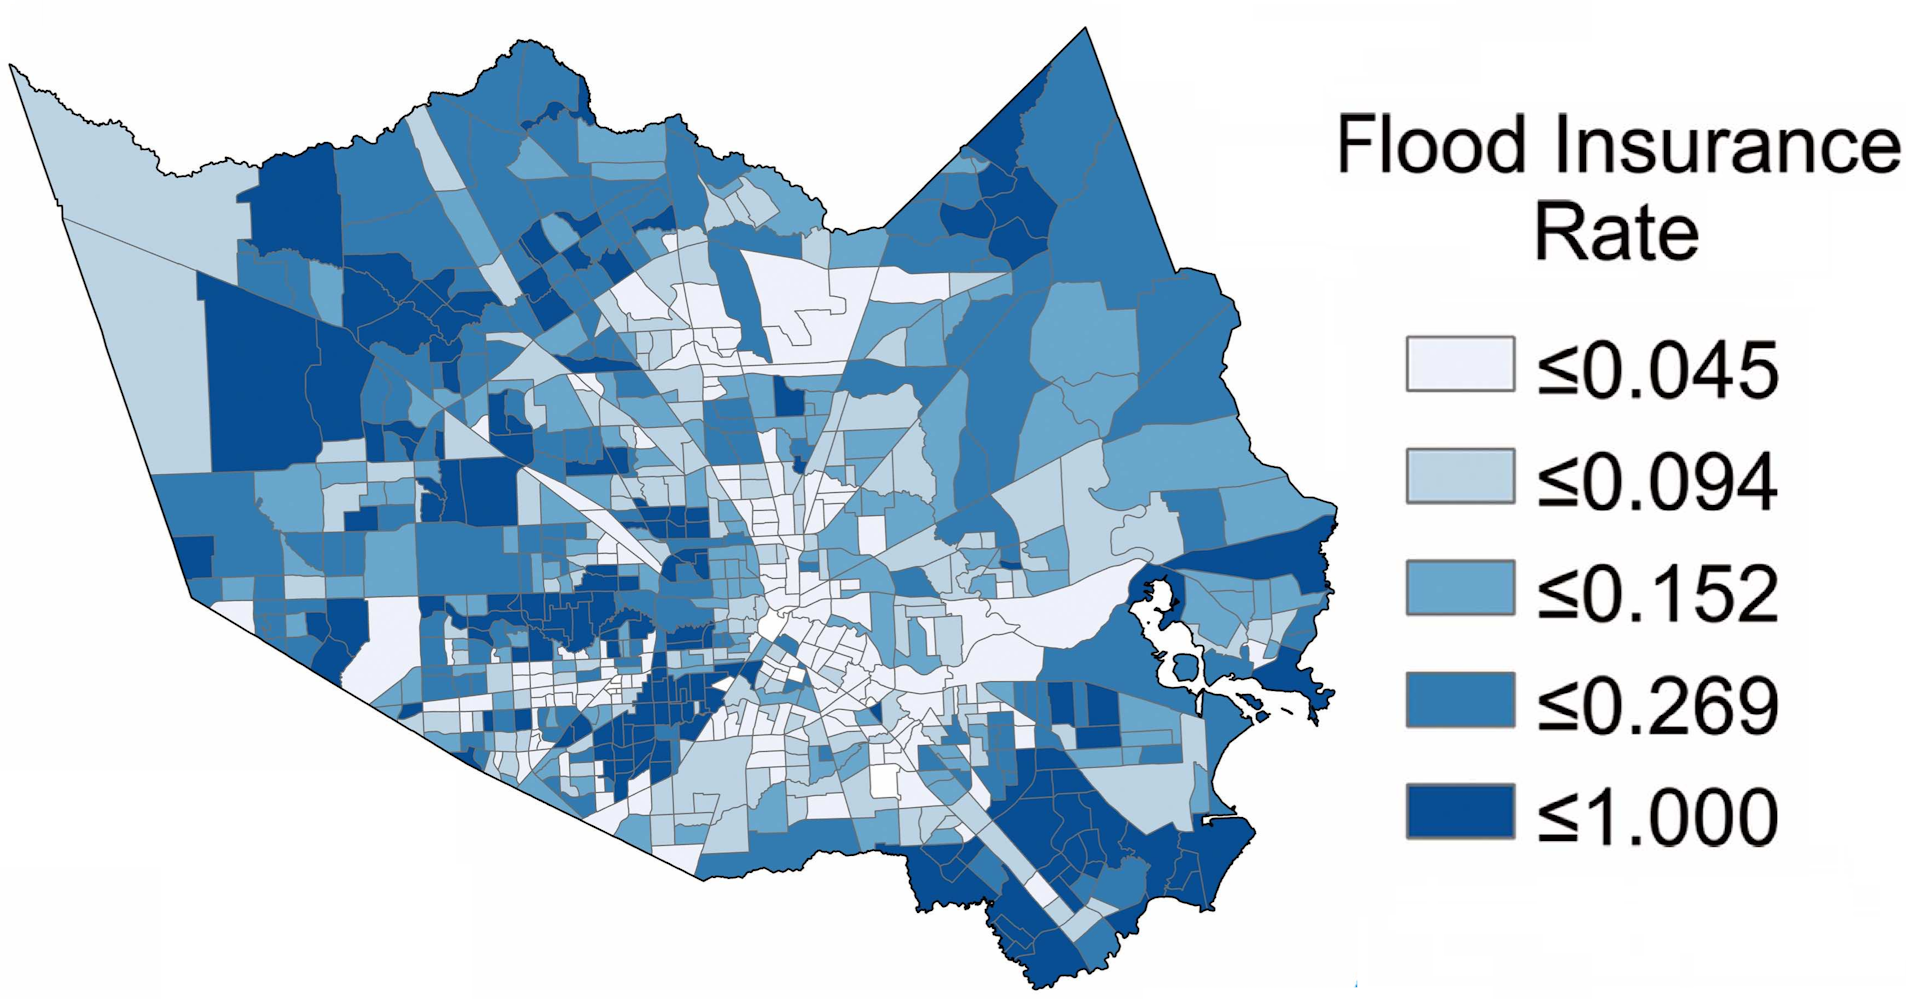


If your home isn’t in a federally designated flood zone, flooding might seem like someone else’s problem. No one requires you to buy flood insurance, and the map suggests you’re in the clear. But reality may be very different.
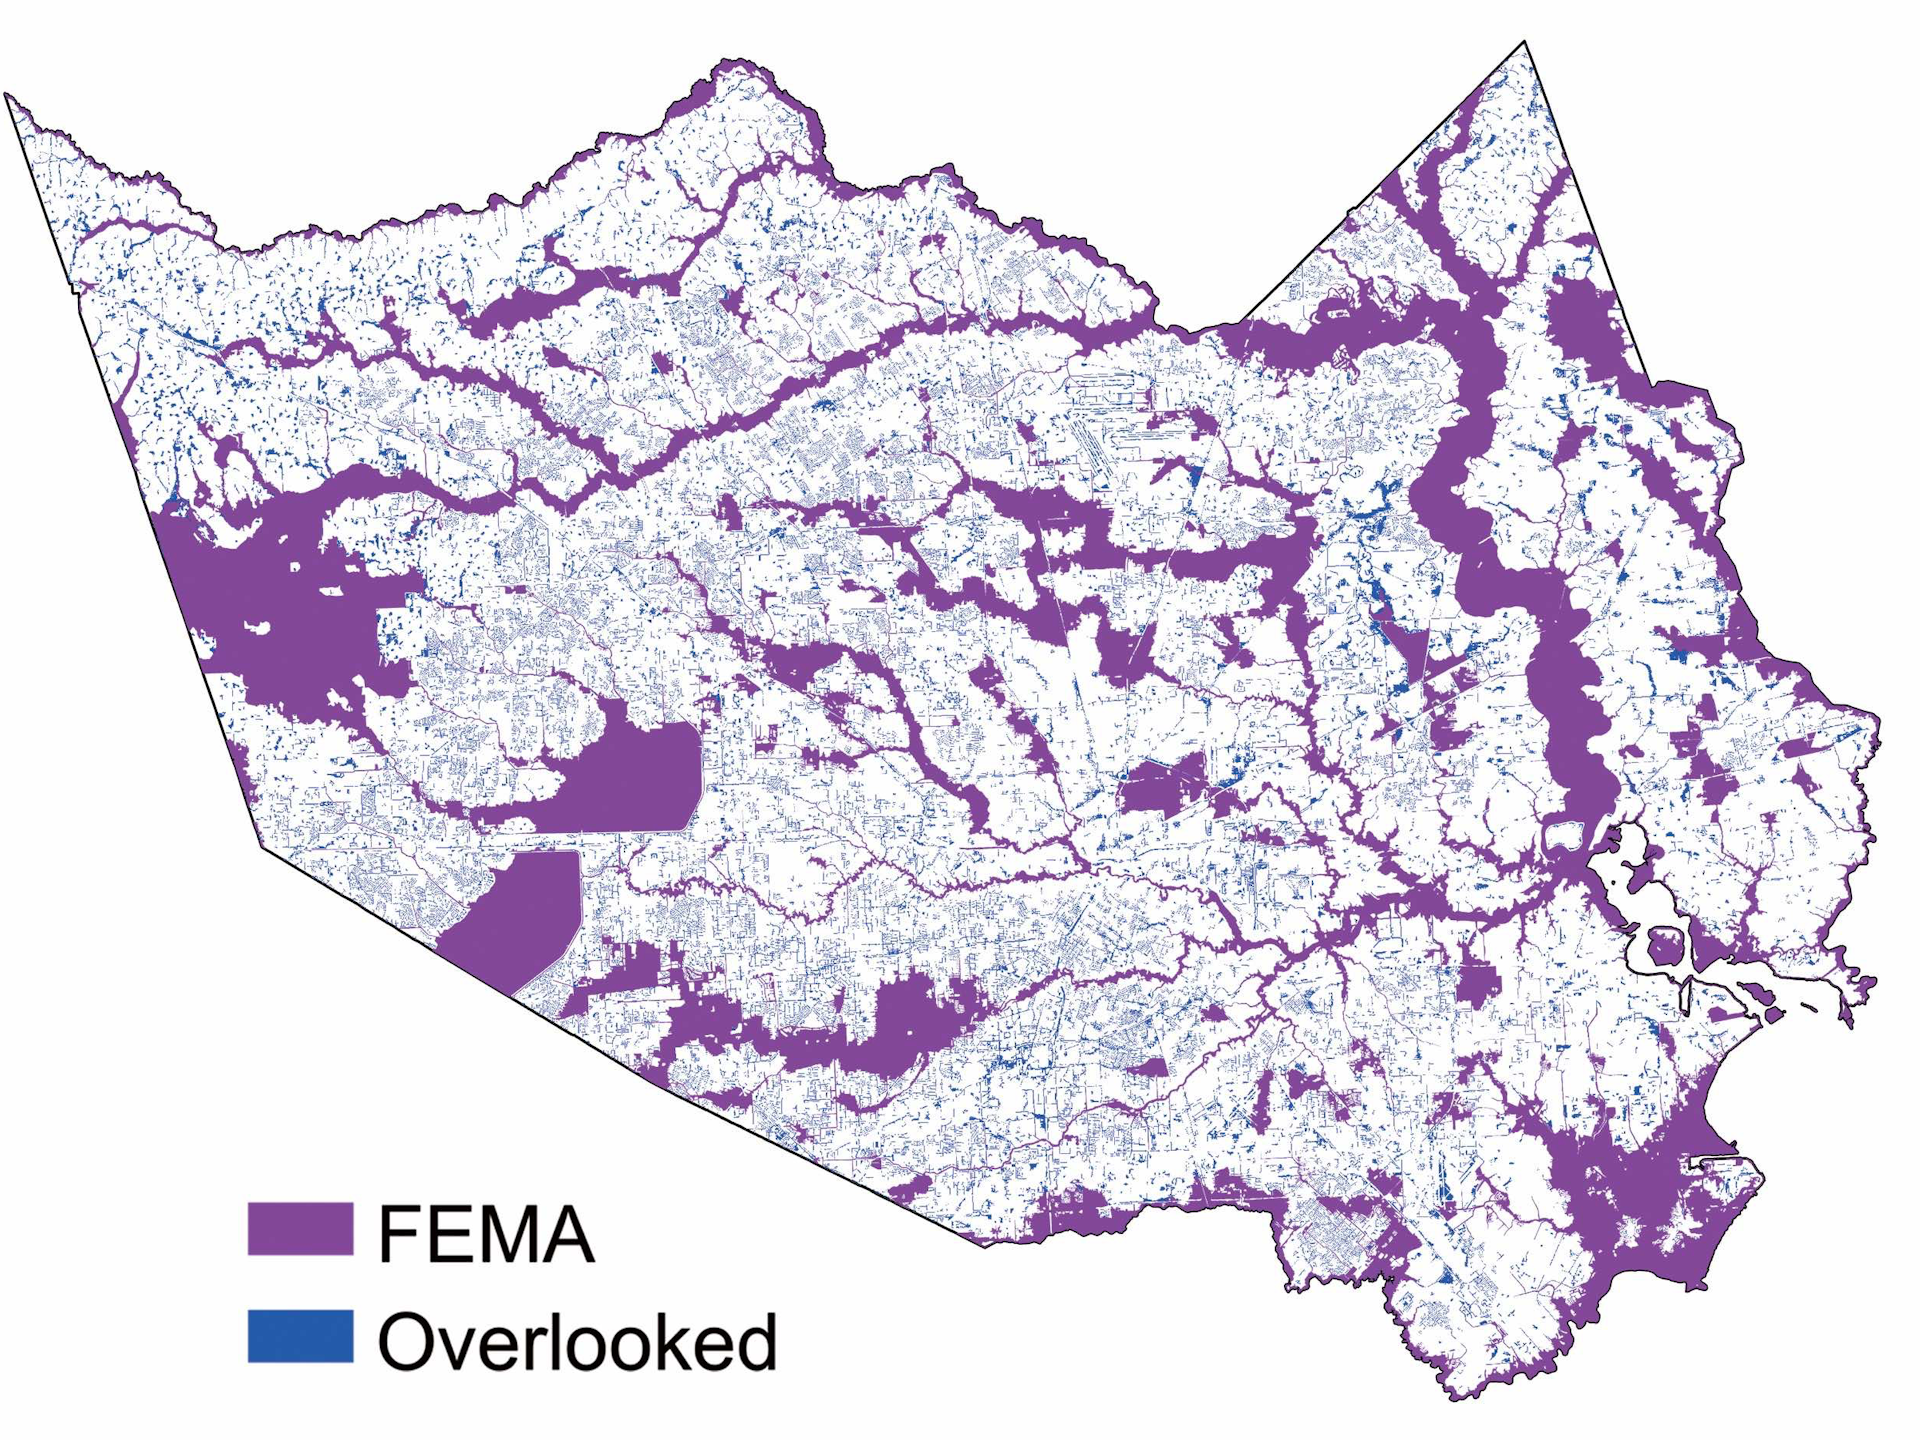
Mounting evidence reveals that significantly more homes are at risk of flooding than is indicated by FEMA’s 100-year flood maps – about 6 million more, and 14.6 million properties in all, by one estimate. The official maps are commonly outdated, and some are two decades old. Even when updated, they typically rely on historical flood data rather than future risk projections.
But there’s another problem that redrawing the lines won’t solve.
FEMA’s flood maps answer only one question: Is the water likely to reach my neighborhood? They don’t assess an individual home’s risks or what the impacts are likely to be when the water rises.
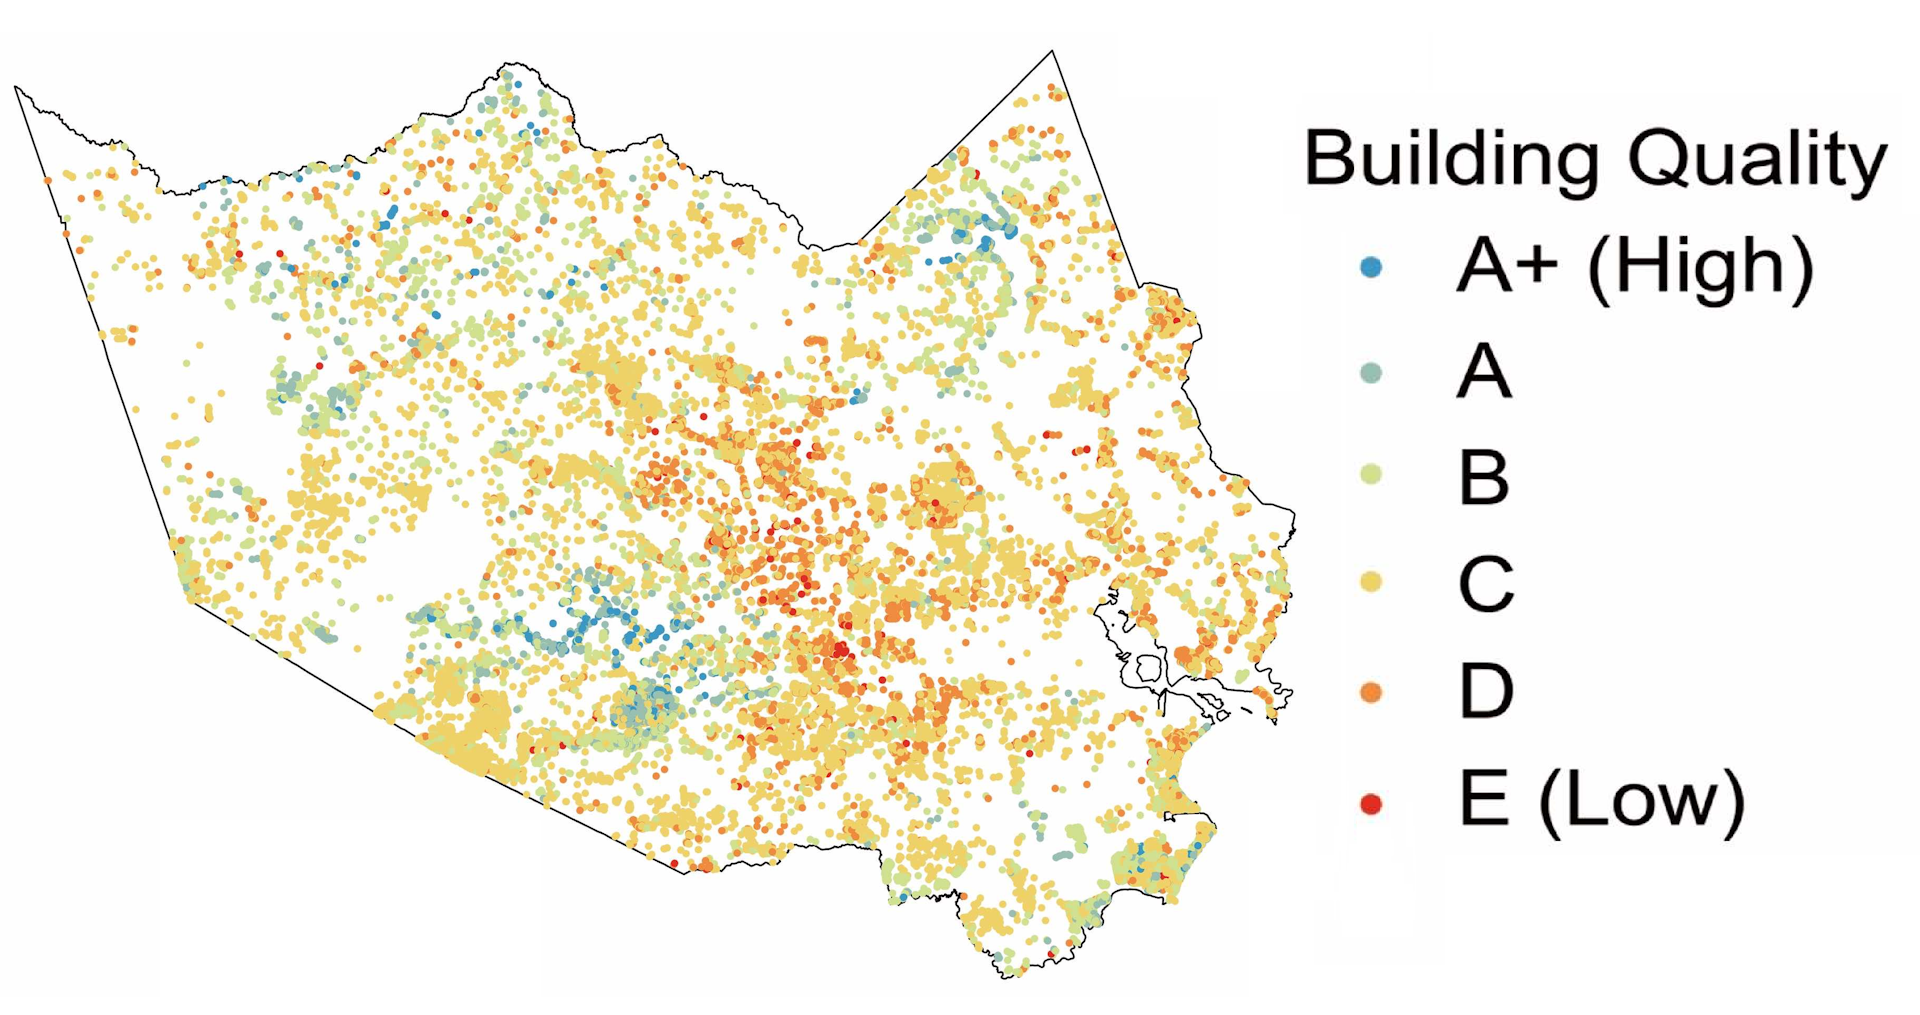
To understand the impact, more comprehensive data is needed, including the probable flood depth at the home, the building’s age and construction quality, and insurance coverage.
When these other factors are considered, your home’s true flood risk is far more complex than the map might seem to indicate.
The data shows how two houses on the same street can face radically different risks from flooding, even when located in the same flood zone – and where local governments can help.
One home may be newer, well maintained and covered by flood insurance. Another may be decades older, at the low end of the same street where water runs deeper during a flood, and is in poor repair and uninsured. The same storm would leave them in very different predicaments, with very different paths to recovery.
Neighborhood averages can make it hard to tell which homes are likely to be hit hardest. But understanding an individual property’s risks matters for residents figuring out how to protect a home, and for local officials deciding where limited flood-protection money should go.
We study how flooding affects homes and the people who live in them. To see how much these house-by-house differences matter, we and colleagues Aaron Flores of Arizona State University and Sara Meerow of the University of Colorado Boulder built a detailed flood risk score for nearly 1 million homes in Houston. We describe the results in a new study published in the journal Applied Geography.
Our past research in Houston found that more than half of 100,000 documented flood-prone buildings in the city currently lie outside official flood boundaries, and that these overlooked buildings are more likely to be in poor condition and uninsured, leaving them especially exposed when the floodwaters do come.
The new research helps communities locate those homes.
To get a better understanding of each household’s vulnerability, we combined four types of information about each home.
We chose these four criteria because flood research consistently highlights their importance for how hard a flood hits a community: how much water arrives, how well the building holds up, whether people can still get around and how big the repair bill is for the owner. They aren’t the only possible measures; a city could use others within each category, depending on available data.
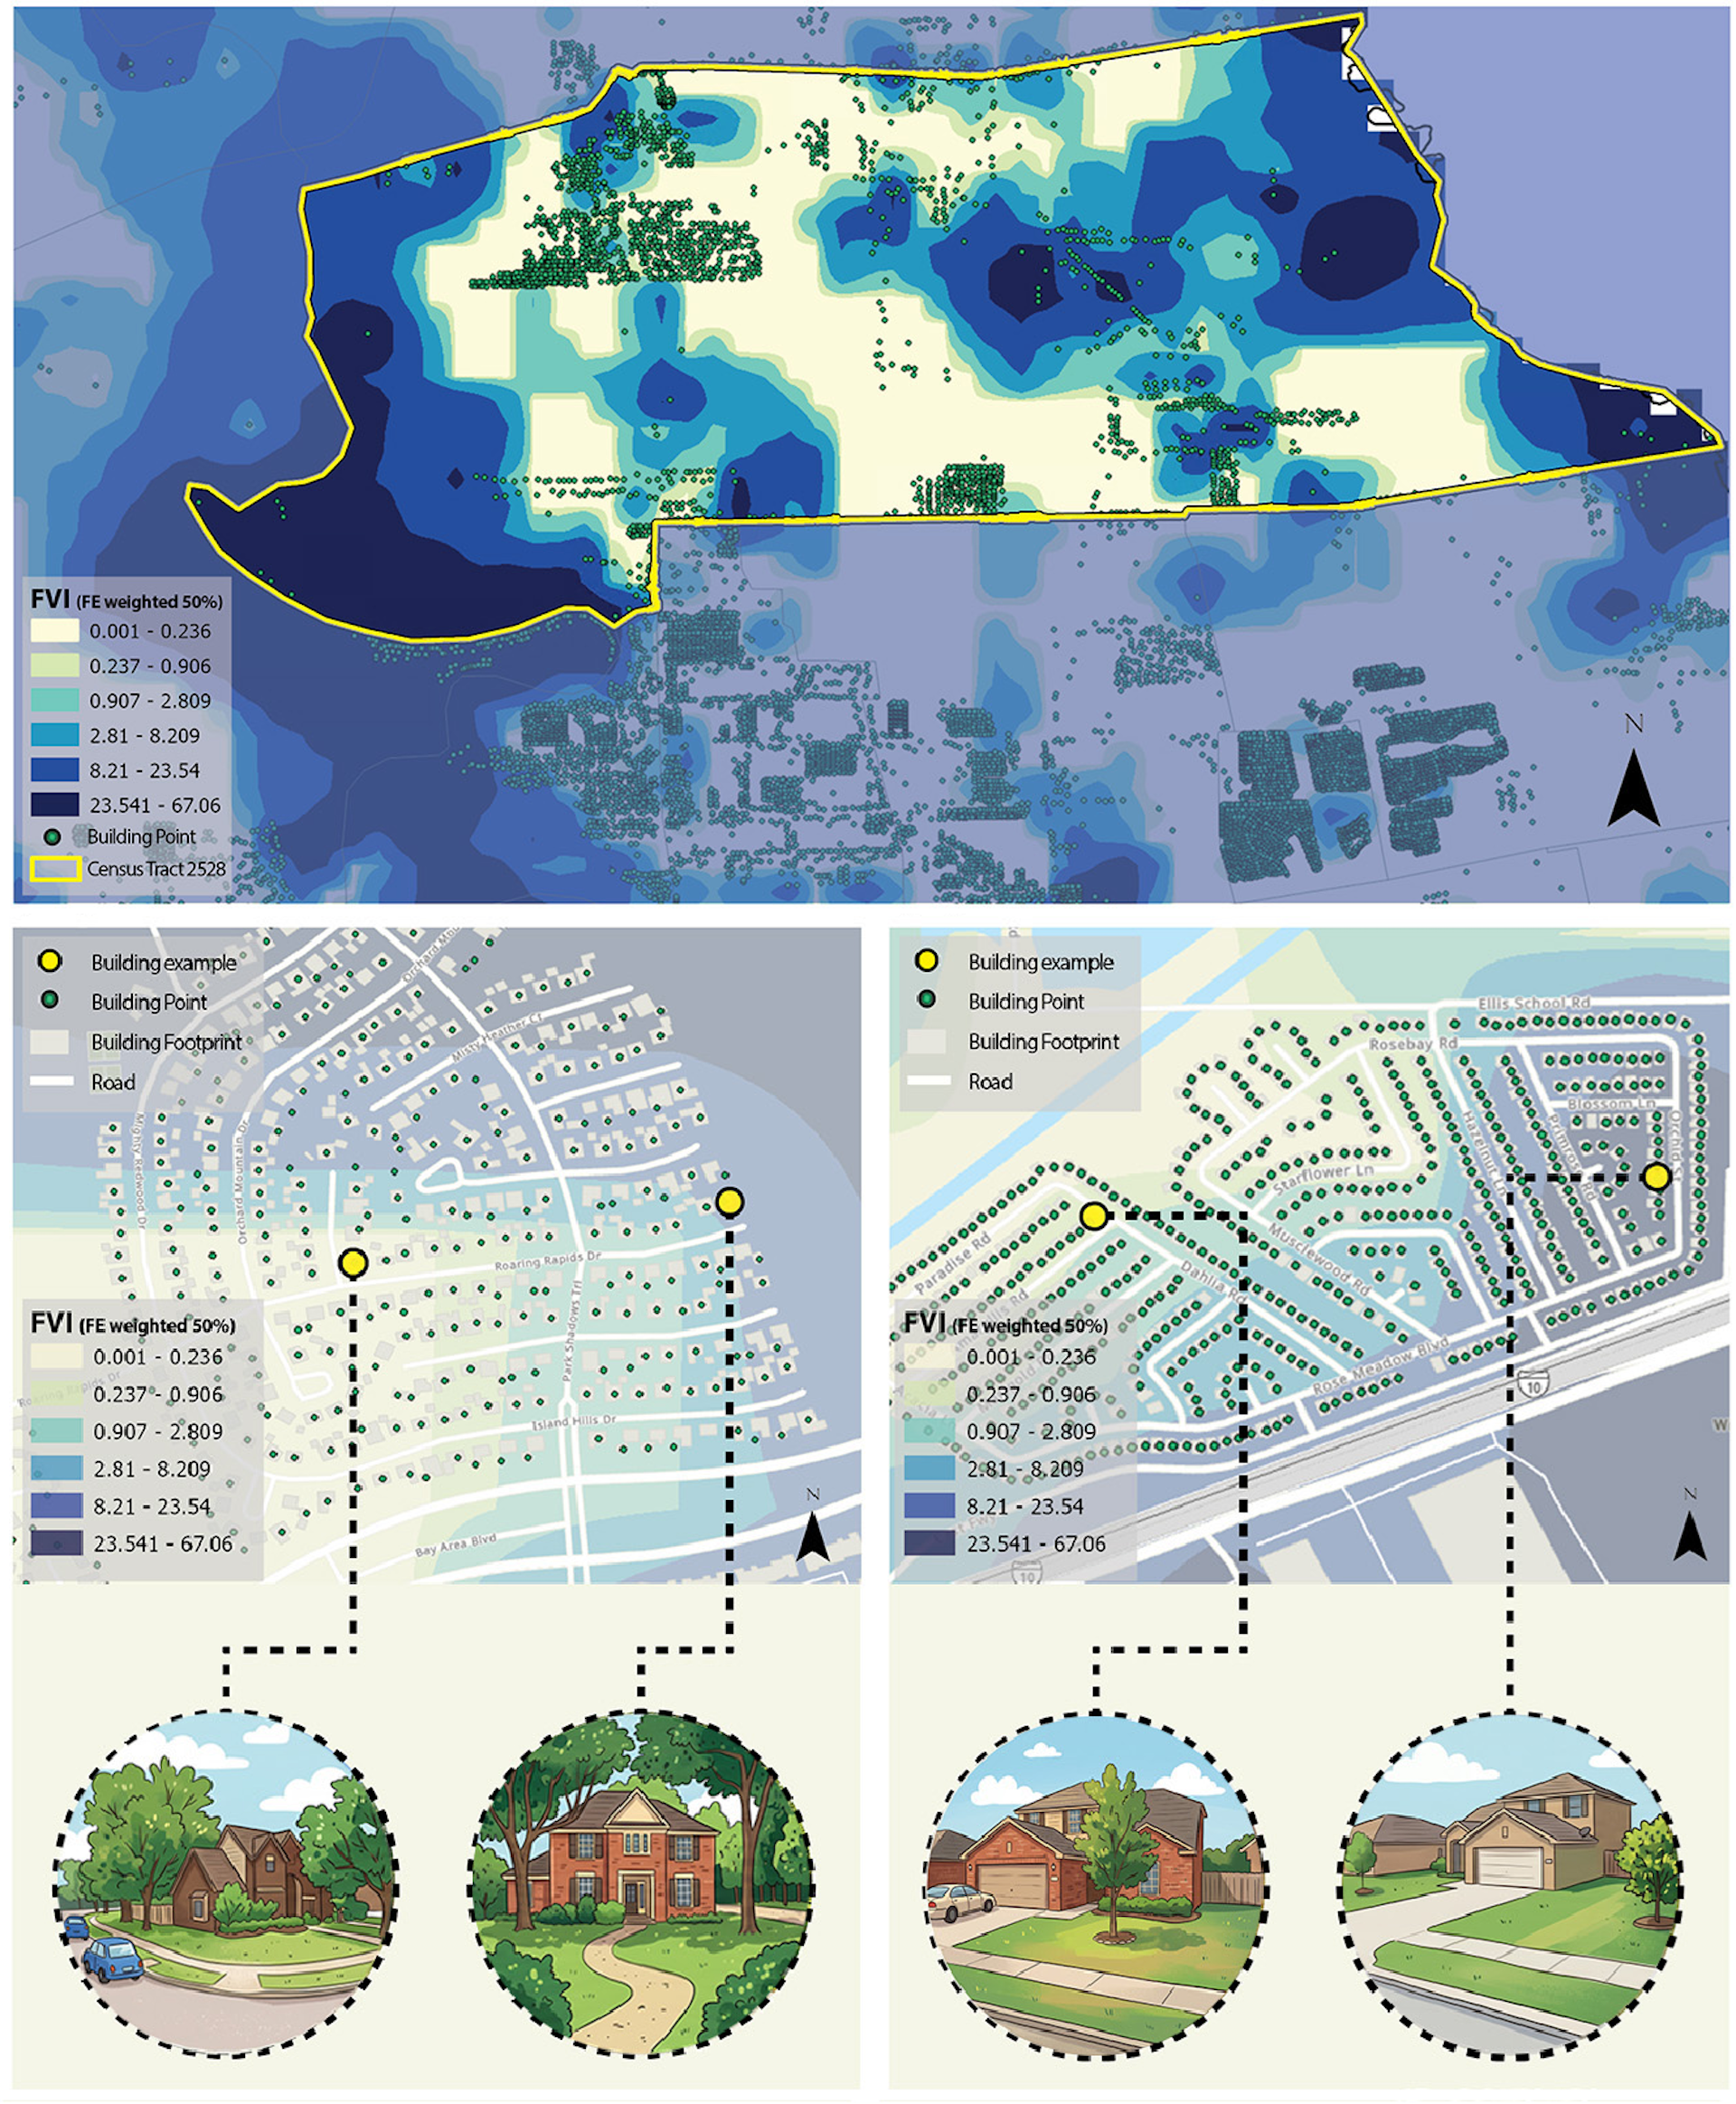
Homes in the same neighborhood can have very different flood vulnerability scores. In fact, we found the scores differed more from house to house within a neighborhood than from one neighborhood to the next.
In practice, this means that knowing a neighborhood’s flood risk doesn’t necessarily tell you how hard a flood could hit any individual home. A neighborhood could look safe on average while containing some of the county’s riskiest homes, and there may be many well-protected homes in an otherwise risky neighborhood. Much of the problem, we show, lies at the scale of buildings, not neighborhoods or ZIP codes.
Homeowners can check several of these risks themselves.
Ask longtime neighbors or your city’s flood plain office whether your home or the street has been flooded before. Look up the home’s age in local property records and have an inspector assess its condition. Find out whether the routes to work and school flood easily. And check whether you have a flood insurance policy, and what it covers: Most homeowner’s policies don’t cover flood damage.
Communities can apply our approach with their own data to locate particularly vulnerable housing where neighborhood averages may disguise the need for help. They can start with existing address-level flood scores, such as First Street’s, and add local records on buildings, roads and insurance. The extra details matter because officials have limited money for flood-proofing homes, improving drainage and helping families recover after floods. Better data on buildings and flood risk can help them invest wisely.
Data similar to that used for Houston exists across much of the United States, so other flood-prone cities could follow the same approach.
Floods don’t stop at the lines on a map, and they don’t hit every house on a street the same. We believe it’s time for residents and local flood authorities to prepare accordingly.
This article is republished from The Conversation, a nonprofit, independent news organization bringing you facts and trustworthy analysis to help you make sense of our complex world. It was written by: Yilei Yu, Rice University; Dylan Connor, Arizona State University, and James R. Elliott, Rice University
Read more:
When homes flood, who gets FEMA buyouts and where do they go? We mapped thousands of moves and found distance and race both play a role
Flood maps show US vastly underestimates contamination risk at old industrial sites
What if Texas’ destructive Tax Day storm had centered on inner Houston instead? It’s why cities should plan for the improbable
Yilei Yu receives support from Rice University’s Center for Coastal Futures and Adaptive Resilience and has received support from the School of Geographical Sciences and Urban Planning at Arizona State University.
Dylan Connor receives funding from the National Science Foundation and the National Institute of Health.
James R. Elliott receives funding from the Russell Sage Foundation.

Comments