Elizabeth Warren blasts GM over $20 billion buyback plan
Published in Business News
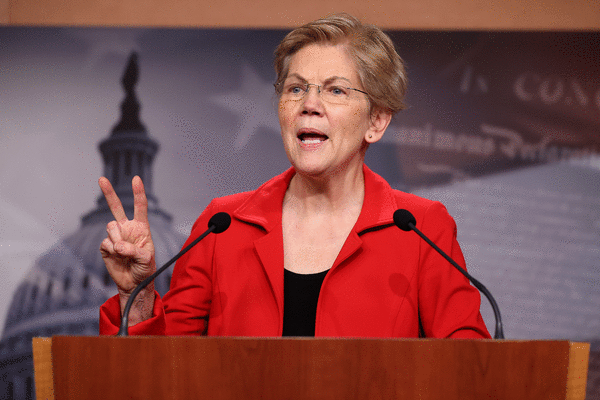
Sen. Elizabeth Warren called out General Motors Co. for buying back billions of dollars in stock at a time when car prices are hitting record highs, joining Senator-elect Abdul El-Sayed in criticism of the automaker’s financial moves.
In a letter to GM Chief Executive Officer Mary Barra, Warren cited the company’s announcement last month that it had authorized the purchase of $20 billion of shares. The multiyear buyback has no expiration date. GM already has put $29.5 billion toward buybacks since 2023.
“This proposal will enrich company executives and shareholders, but it comes after GM hiked its prices and laid off or furloughed thousands of workers,” the Massachusetts Democrat wrote in the letter, which was seen by Bloomberg. “GM’s decision to prioritize investor profits over workers and American families, despite benefitting from President Trump’s tax giveaways and tariff exemptions and refunds, is deeply concerning,” she said.
GM said in a statement that investing in its business and employees is its top priority, with more than $100 billion being put toward growth initiatives since 2020. The new authorization “is a meaningful statement of confidence in GM’s ability to fund growth, reward our U.S. employees with the highest profit sharing in the industry, while also returning capital to our shareholder owners.”
While it’s not uncommon for Warren to call out companies, such criticism carries additional weight after Democrats secured control of the Senate and House of Representatives in the midterm elections. Warren is set to become chair of the Senate Committee on Banking, Housing and Urban Affairs when the new Congress is sworn in in January.
The previously unreported comments echo El-Sayed’s criticism of the carmaker during his campaign for Senate in GM’s home state of Michigan. It became a rare point of agreement between the candidate and his opponent, Republican Mike Rogers, both of whom denounced the plan.
“GM just announced the biggest stock buyback in automotive industry history,” El-Sayed wrote in an X post last month. “Instead of investing in their workers or new product lines, GM executives are robbing from the future to pay themselves and their shareholders today.”
Strong profits
The automaker has sought to boost its stock value through repurchases while it brings in strong profits from sales of pricey models like its large pickups and full-size SUVs. GM has laid off workers, including a round last year tied to a pullback in electric vehicle production, as it has reckoned with tepid demand for plug-in automobiles.
President Donald Trump ended the Biden-era $7,500 tax credit for EV purchases and cut the penalties for missing federal fuel economy rules, which had pushed automakers to sell money-losing battery-powered vehicles. Even before the sales incentives were cut, it was clear American consumers weren’t adopting EVs as fast as automakers had planned.
GM has written down more than $11 billion in EV investments and other automakers, including Ford Motor Co., Honda Motor Co. and Stellantis NV have taken big writedowns, as well.
The buybacks have helped GM’s share price, which has more than doubled since the start of 2023, when it stepped up moves to acquire more of its own stock. The latest buyback plan wasn’t enough to overcome GM’s warning when announcing third-quarter earnings that it sees choppy waters ahead. Shares fell almost 7% that day.
©2026 Bloomberg L.P. Visit bloomberg.com. Distributed by Tribune Content Agency, LLC.
Comments