Real estate Q&A: Our insurance company says flood damage isn't covered. What do we do now?
Published in Business News
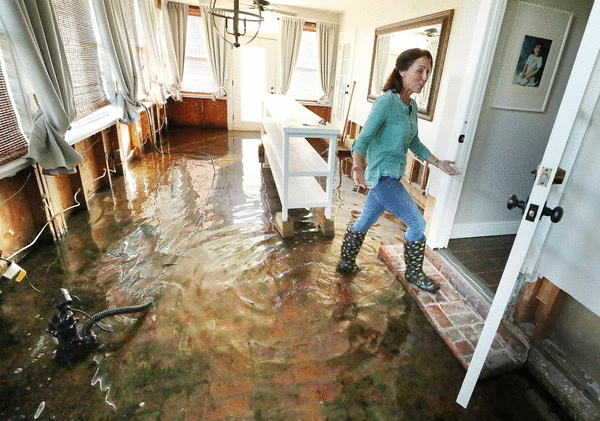
Q: During the heavy rains [a couple weeks ago], water came into our home. It soaked the carpet in our family room and ruined much of what we had in the garage. When we called our insurance company, they told us flooding is not covered. Is there anything we can do, and what should we do so this does not happen to us again? — Linda
A: I am sorry you are dealing with this. Water damage is miserable to clean up, and it is even worse when you are told your insurance will not help. Before you accept that answer, take a closer look at your coverage and at how the water entered your home.
Start by checking whether you already have a flood policy. A surprising number of people have one and do not know it. Some lenders require flood coverage at closing. Some buyers take over the seller’s policy. Some homeowners bought a policy years ago and forgot about it because the premium is paid through their mortgage escrow. Review your escrow statement and closing papers, or call your insurance agent to confirm. If you live in a condominium, your association may also carry flood coverage on the building.
Next, look at how the water got in, because that matters. A standard homeowners policy does not cover flooding, which is water that rises from the ground outside and flows into your home.
It often does cover water that enters because the storm damaged your roof or broke a window, as well as water from a burst pipe. If any of your damage came in that way, ask your insurer to take another look.
Take photographs of everything before you throw anything away, and ask for the denial in writing.
If you do not have flood coverage, now is the time to consider getting it.
Flood insurance is a separate policy, and there are two main types. The first is through the federal flood insurance program, which most insurance agents can sell you. It covers up to $250,000 for the house and up to $100,000 for your belongings. It does not pay for a hotel if you have to move out during repairs.
The second type is private flood insurance. These policies can offer higher limits, and many will pay your living expenses while your home is being repaired. Prices vary, so get quotes on both.
You also need to know about waiting periods. A federal flood policy generally does not take effect until 30 days after you buy it, unless you buy it at the time of a home closing. Private policies often have shorter waiting periods, sometimes a week or two, but each company is different.
Either way, you cannot wait until a storm appears in the forecast. By then, it is too late.
Do not take too much comfort in being outside a flood zone. More than 20 percent of federal flood insurance claims come from homes outside high-risk areas, and coverage there usually costs less.
Also keep in mind that Congress must keep renewing the federal program. When it lapsed last year, no new policies could be sold for weeks.
Once you have had water in your home, I would not wait to see if it happens again. Call your agent this week to get a quote.
©2026 South Florida Sun Sentinel. Visit at sun-sentinel.com. Distributed by Tribune Content Agency, LLC.
Comments